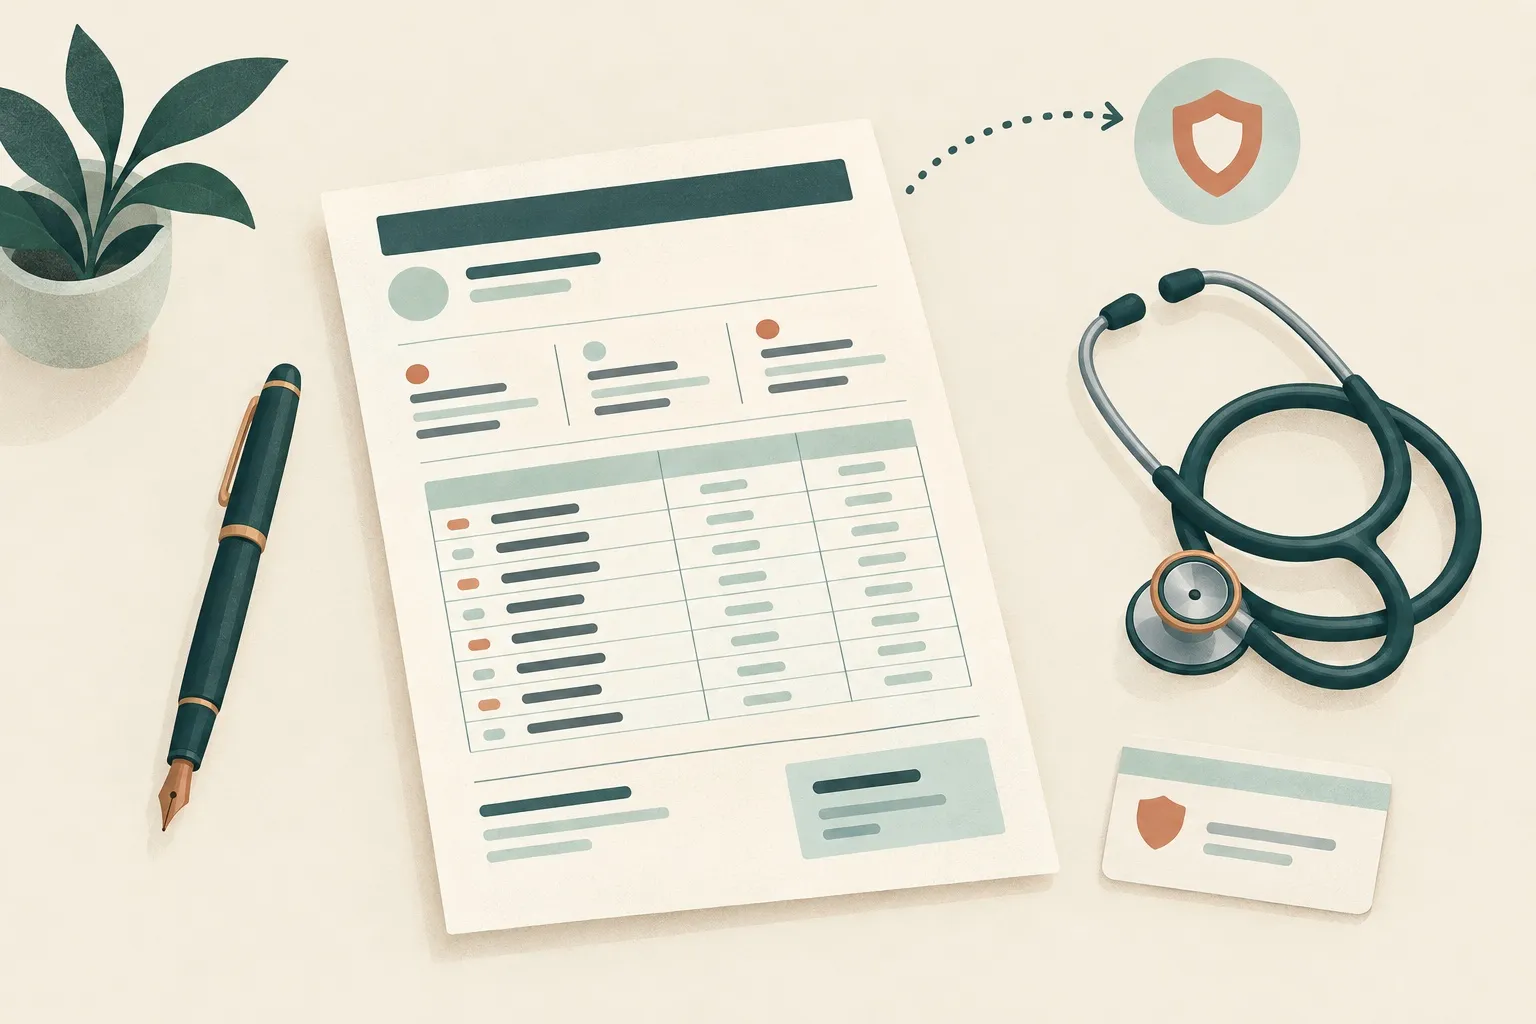
A superbill for therapy is an itemized statement from your therapist that lists your sessions, the diagnosis and procedure codes for each one, the fees, and what you paid. You submit it to your health insurance company to request out-of-network reimbursement, or keep it as documentation for an HSA or FSA. Your therapist creates it; you file it.
If your therapist doesn’t take your insurance, a superbill is how you can still use your out-of-network benefits. Here’s how it works from the client side, what should be on it, and how to get reimbursed faster.
Why do therapists give superbills instead of billing insurance?
Many therapists choose not to join insurance networks. Being in network means accepting the insurer’s contracted rates, handling claims and authorizations, and following the insurer’s documentation rules. Private-pay therapists set their own fees and collect payment at the time of service instead.
A superbill bridges the gap. You pay your therapist directly, and your therapist gives you the coded documentation your insurer needs so you can seek reimbursement yourself. Some clients choose a private-pay therapist even when an in-network option exists, for reasons like fit, availability, or a specific specialty.
How do therapy clients use a superbill?
- Check your benefits. Call your insurer and ask about out-of-network coverage for outpatient mental health, your deductible, your coinsurance, and whether telehealth is covered.
- Pay for your sessions. Your therapist collects their fee as agreed.
- Get the superbill. Per session or monthly, depending on your therapist’s practice.
- Submit it with your insurer’s claim form through the member portal, mobile app, or mail.
- Watch for the explanation of benefits (EOB) and reimbursement.
Our full guide on how to submit a superbill to insurance covers claim forms, deadlines, and denials step by step.
What’s on a therapy superbill?
A complete therapy superbill contains:
- Therapist information: name, credentials (for example LCSW, LMFT, LPC, or PsyD), practice name and address, phone, NPI, Tax ID or EIN, and license number
- Your information: name, date of birth, address, insurance carrier, member ID, and group number
- Diagnosis: at least one ICD-10 code, such as F41.1 for generalized anxiety disorder
- Each session: date, CPT code, any modifier, place of service code, diagnosis pointer, units, and fee
- Payment: total charges, amount paid, and balance
- Signature: your therapist’s signature and the date
A note on privacy
Insurers won’t reimburse without a diagnosis code, so a therapy superbill always includes one, and submitting it means your insurer will have that diagnosis on record. Some clients decide not to submit for that reason. It’s a personal choice, and if you’re unsure, it’s worth discussing with your therapist.
Common CPT codes on therapy superbills
Most therapy superbills use a small set of psychotherapy codes. The descriptions below are short, plain-language summaries. Your therapist chooses the code that matches the service actually provided.
| CPT code | What it’s generally used for |
|---|---|
| 90791 | Initial diagnostic evaluation (intake), usually the first session |
| 90832 | Individual psychotherapy, about 30 minutes |
| 90834 | Individual psychotherapy, about 45 minutes |
| 90837 | Individual psychotherapy, about 60 minutes |
| 90846 | Family or couples session without the client present |
| 90847 | Family or couples session with the client present |
| 90853 | Group psychotherapy |
The individual psychotherapy codes are based on the time spent with you, so the same client might have 90834 one week and 90837 the next if a session runs longer. For details on each of the most common codes, read our guides to CPT 90791, CPT 90834, and CPT 90837.
Coverage for each code depends on your plan. When you call your insurer, give them the exact code your therapist bills so they can tell you how they would process it.
Does your therapist’s license type matter?
It can. Plans generally reimburse out-of-network therapy only when it’s provided by a licensed clinician whose license type the plan recognizes, such as a psychologist, licensed clinical social worker, licensed marriage and family therapist, or licensed professional counselor. Recognized license types vary by plan and by state.
Policies on pre-licensed clinicians (associates or interns practicing under supervision) vary even more. Some plans won’t reimburse their services at all, and others have specific rules about how the supervisor must appear on the claim. If your therapist is pre-licensed, ask your insurer how it handles that before you start submitting, and share the answer with your therapist so the superbill matches.
Questions to ask your therapist about superbills
A short conversation at the start of therapy prevents most reimbursement headaches. Useful questions:
- Do you provide superbills, and is there a charge?
- Will I get one after each session or once a month?
- Which CPT code do you usually bill for our sessions?
- Will telehealth sessions be coded differently from in-person sessions?
- Does the superbill include your NPI, Tax ID, and license number?
- If my insurer asks for a correction, can you issue an updated superbill?
With the CPT code in hand, you can call your insurer and get a much more specific answer about what they would allow and reimburse.
How does telehealth therapy appear on a superbill?
Telehealth sessions usually use the same CPT codes as in-person sessions, plus a place of service (POS) code and sometimes a modifier:
- POS 10: telehealth when you’re at home
- POS 02: telehealth when you’re somewhere other than home
- Modifier 95 or GT: used by some payers to flag a session as telehealth
Insurers don’t all follow the same rules. Some want POS 10 with modifier 95, some want POS 02, and some want no modifier at all. If a telehealth claim is denied, ask your insurer what it expects and pass that along to your therapist. Our explainer on place of service codes for telehealth goes into more detail.
Monthly vs. per-session therapy superbills
| Per-session superbill | Monthly superbill | |
|---|---|---|
| Reimbursement timing | Faster, since you can submit right away | Slower, since you wait until month end |
| Paperwork | More documents to track and upload | One document per month |
| Deadline risk | Low | Low, if you submit promptly each month |
| Best for | Clients who want money back quickly or have short filing windows | Most clients in weekly therapy |
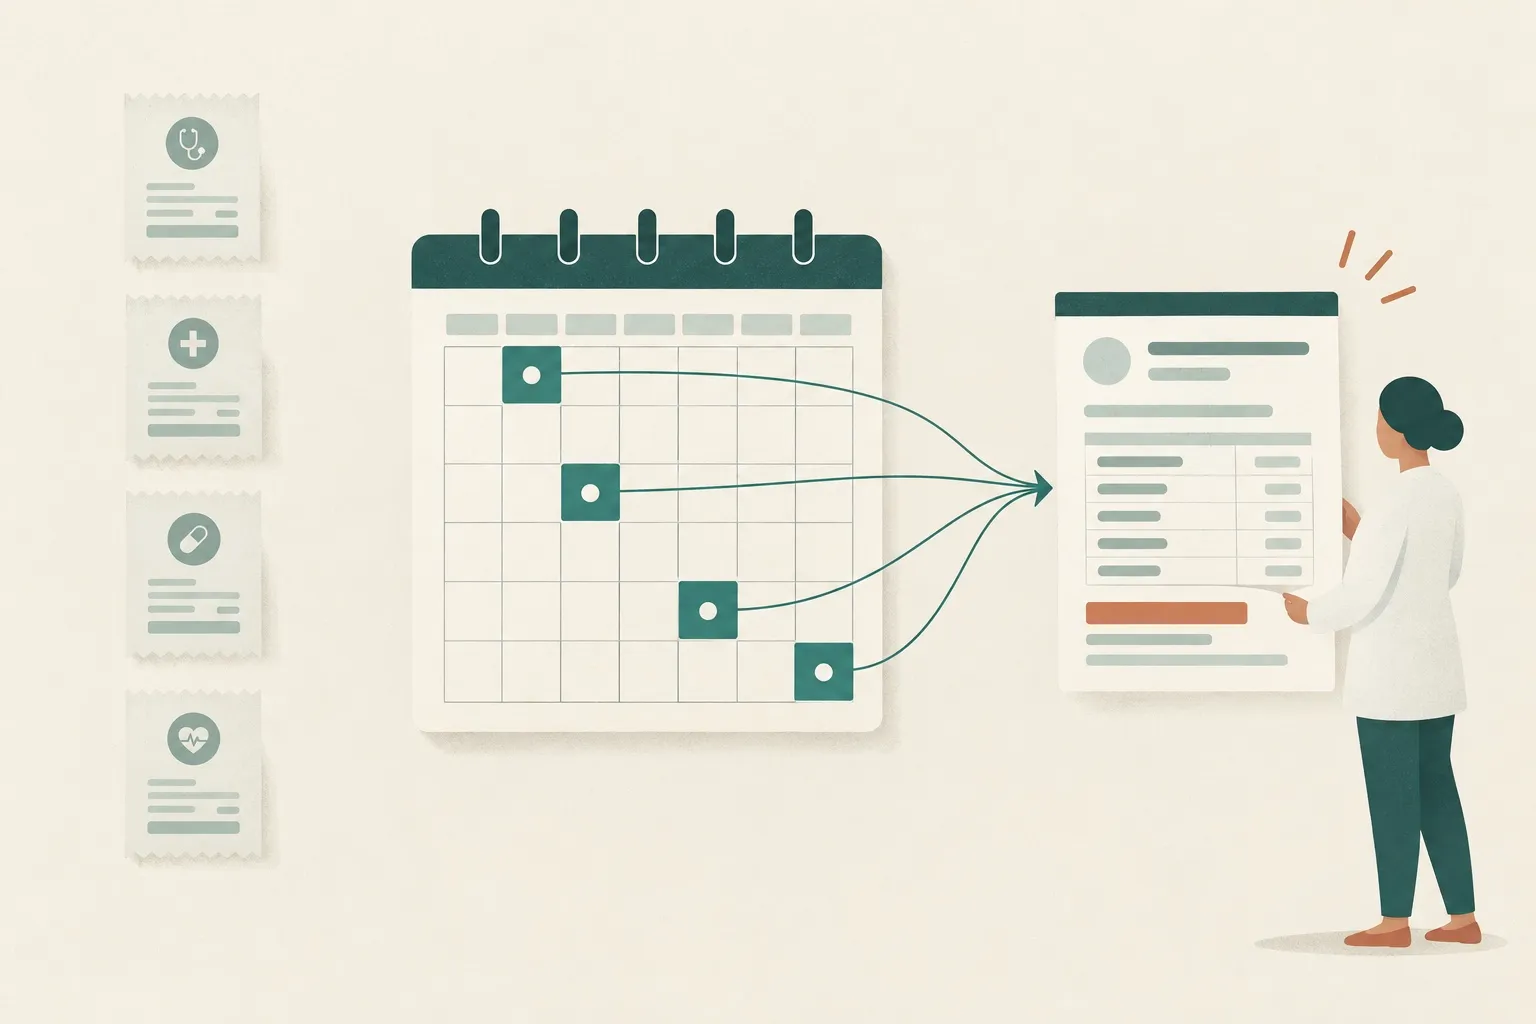
Monthly superbills are the most common setup for weekly therapy. Each session still gets its own line with its own date, code, and fee.
What should therapists include on a superbill?
If you’re a therapist, a complete superbill saves your clients phone calls and saves you correction requests. Make sure every superbill has:
- Your individual (Type 1) NPI, plus your group NPI if you bill under a group
- Your Tax ID or EIN and your license number
- A diagnosis pointer on every service line
- The place of service code and modifier the client’s insurer expects for telehealth
- The amount paid, the balance, and your signature
Our therapist superbill template comes preloaded with the common psychotherapy codes above. If you keep session records in an EHR or spreadsheet, you can import a CSV export and print a monthly superbill for every client at once.
Tips to get reimbursed faster
- Verify benefits first. Know your out-of-network deductible and coinsurance before your first claim.
- Submit even before you meet your deductible. Claims applied to your deductible still count toward meeting it.
- Check the superbill before uploading. Confirm that your name, date of birth, and member ID match your insurance card.
- Use the portal when you can. Online submissions are easier to track than mail.
- Keep a log. Note submission dates, claim numbers, and amounts reimbursed.
- Watch the filing deadline. Each plan sets its own limit, and late claims can be denied.
- Follow up on anything stalled. Call with the claim number in hand.
Does a therapy superbill guarantee reimbursement?
No. The superbill gives your insurer the information it needs, but your plan decides what it covers. A plan without out-of-network benefits, an unmet deductible, a prior authorization requirement, or a visit limit can all reduce or block reimbursement. Checking your benefits before you start therapy is the best way to know what to expect.
Therapists: create a therapy superbill now. It’s free, there’s no account, and your data stays in your browser.
FAQ
Do all therapists provide superbills?
Many private-pay and out-of-network therapists provide superbills, often at no extra charge, but it isn't universal. Ask during your consultation whether they issue superbills and how often.
Will my diagnosis be on my therapy superbill?
Yes. Insurers require at least one ICD-10 diagnosis code to process a reimbursement claim, so your therapist will include one. If you have privacy concerns, talk them through with your therapist before deciding whether to submit to insurance.
Can I use a therapy superbill for couples counseling?
Sometimes. Insurers typically cover therapy that treats a diagnosed condition of an identified patient, and some plans don't cover couples counseling on its own. Ask your insurer how it handles family psychotherapy codes such as 90847 before you submit.
How often should I ask my therapist for a superbill?
Monthly is common because it keeps paperwork low while leaving plenty of time before most filing deadlines. If you want reimbursement sooner or your plan has a short deadline, ask for one after each session.
Can I use a therapy superbill with my HSA or FSA?
Often, yes. HSA and FSA administrators commonly accept an itemized statement like a superbill as documentation for eligible medical expenses. Check your plan administrator's documentation rules to be sure.