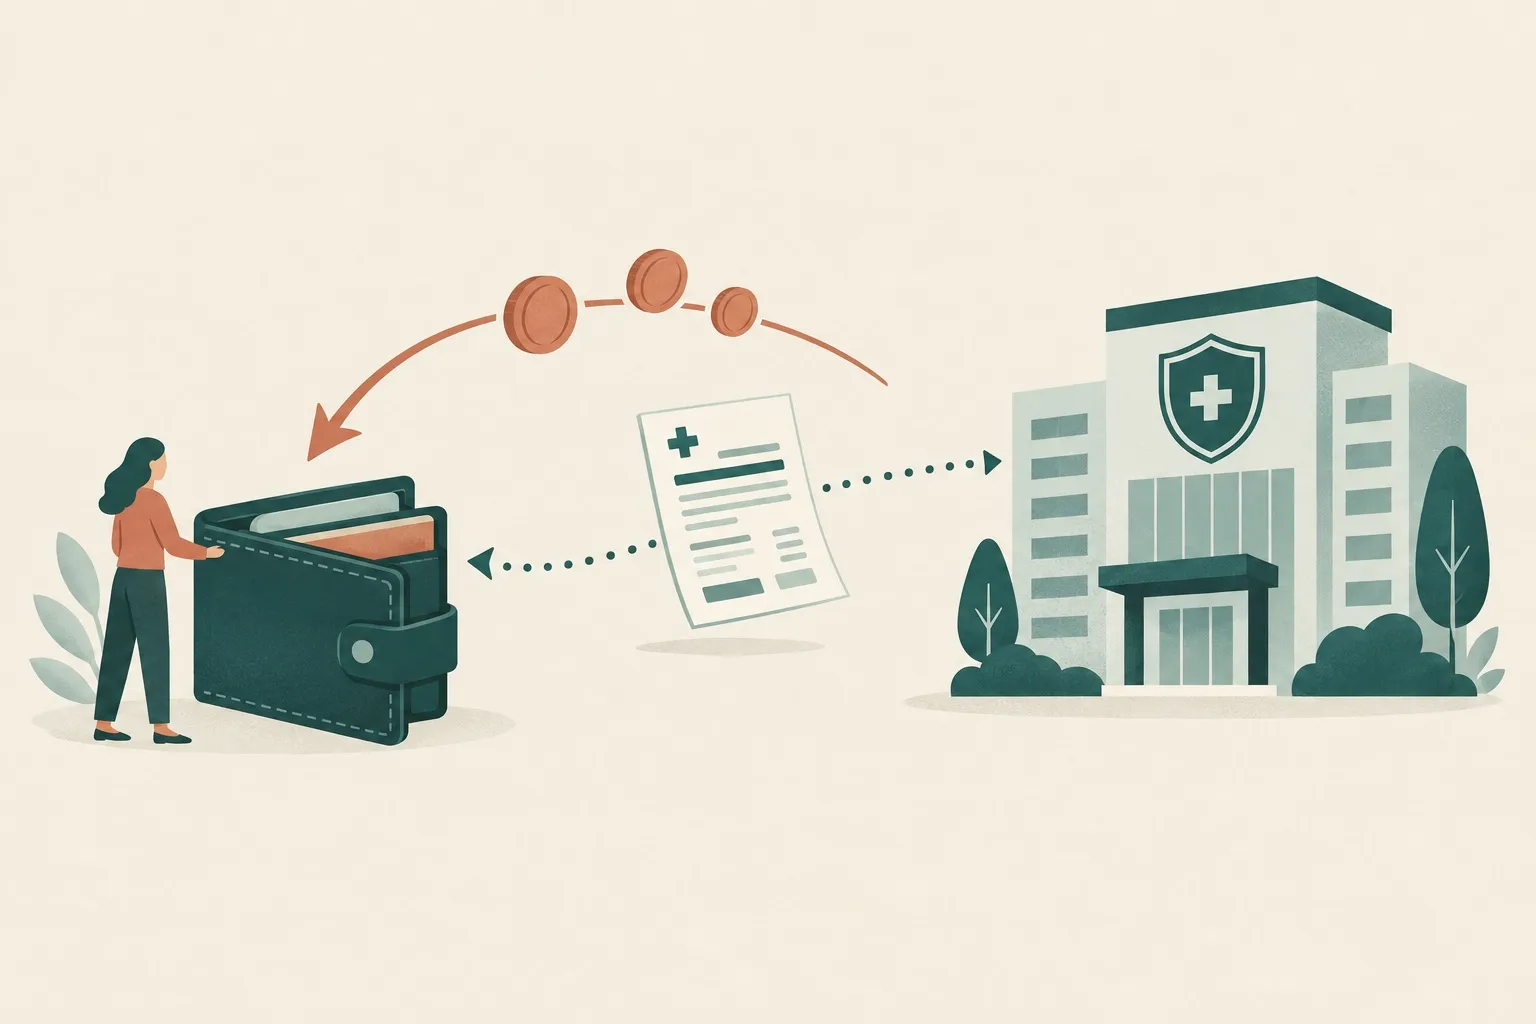
Out of network reimbursement is when your health plan pays you back for part of the cost of care from a provider who isn’t contracted with that plan. For therapy, you usually pay the therapist in full, submit a superbill to your insurer, and, if your plan includes out-of-network benefits, the insurer reimburses a percentage of its allowed amount once you’ve met your out-of-network deductible.
Whether that ends up being a meaningful amount depends on four things: whether you have out-of-network benefits at all, your out-of-network deductible, your coinsurance, and the insurer’s allowed amount for the service. This guide explains each one, gives you a script for calling your insurer, walks through a hypothetical example, and covers how to submit claims.
How does out of network reimbursement work?
The basic sequence is the same at most insurers:
- You pay your therapist directly at the time of service or on a monthly invoice.
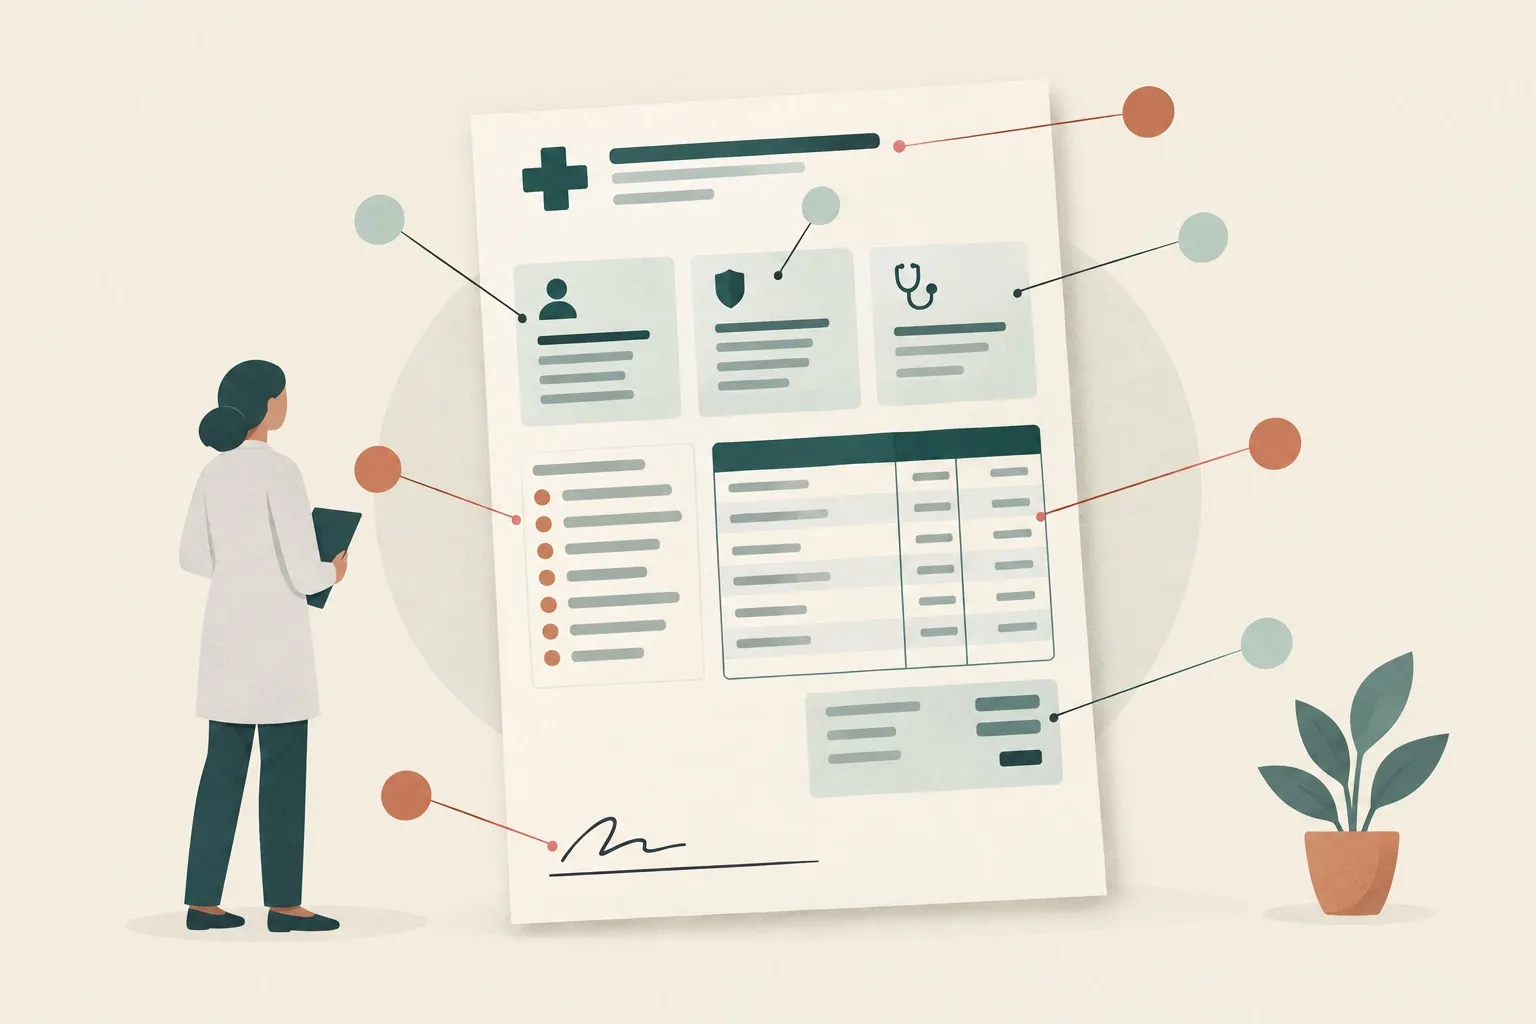
- Your therapist gives you a superbill, an itemized statement listing the provider’s details, your diagnosis codes, the procedure codes for each session, dates, fees, and what you paid.
- You submit the superbill to your insurer, usually with the insurer’s member claim form, by portal upload, mail, or fax.
- The insurer processes the claim. It checks your eligibility and benefits, applies its allowed amount, and credits your deductible.
- You receive an Explanation of Benefits (EOB) showing how the claim was calculated, and a payment if one is due.
The insurer pays you, not the therapist, because you already paid the therapist. That’s the key difference from in-network care, where the provider bills the plan and you pay only your share.
Do I have out-of-network benefits?
Not every plan has them. As a general pattern, PPO and POS plans often include out-of-network benefits, while HMO and EPO plans typically cover out-of-network care only in emergencies or special circumstances. But plan designs vary a lot, even within the same insurer, so don’t rely on the plan type alone.
The fastest ways to check:
- Your Summary of Benefits and Coverage (SBC). Look for an “out-of-network provider” column next to outpatient mental or behavioral health services.
- Your insurer’s member portal, which often lists in-network and out-of-network deductibles separately.
- A call to member services using the questions below. This is the most reliable option, because the representative can look up your specific plan.
Key terms: deductible, coinsurance, and allowed amount
These terms determine how much comes back to you.
| Term | What it means for out-of-network therapy |
|---|---|
| Out-of-network deductible | The amount of allowed charges you must pay yourself each plan year before the plan starts reimbursing. Often separate from, and higher than, the in-network deductible. |
| Coinsurance | The percentage split after the deductible. For example, a plan that “pays 60%” leaves you 40% coinsurance. |
| Allowed amount (UCR) | The maximum the insurer recognizes for a service. Insurers set it in different ways, such as a “usual, customary, and reasonable” database, a percentage of Medicare rates, or their own fee schedule. |
| Fee above the allowed amount | If your therapist charges more than the allowed amount, the difference is your responsibility. On many plans it doesn’t count toward your deductible or out-of-pocket maximum. |
| Out-of-pocket maximum | The cap on your cost-sharing for the year. Some plans have a separate out-of-network maximum; some have none for out-of-network care. |
The allowed amount is the one people most often overlook. Your coinsurance applies to the allowed amount, not to what your therapist charges.
What should I ask my insurance company?
Call the member services number on your insurance card and ask for out-of-network benefits for outpatient mental health. Have your member ID, your therapist’s procedure code (commonly 90791 for an intake, 90834 or 90837 for ongoing sessions), and your therapist’s ZIP code ready. Use this list as a script:
- Do I have out-of-network benefits for outpatient mental health services? Do they cover telehealth sessions?
- What is my out-of-network deductible, and how much of it have I met this plan year? Is it separate from my in-network deductible?
- After the deductible, what percentage does the plan pay for out-of-network outpatient therapy?
- What is the allowed amount for CPT code [code] from a provider in ZIP code [ZIP]? If you can’t give a number, how is the allowed amount calculated?
- Is there an out-of-network out-of-pocket maximum?
- Do I need pre-authorization or a referral for out-of-network therapy?
- Is there a limit on the number of sessions per year?
- Does the provider’s license type matter for coverage (for example, psychologist, LCSW, LMFT, or LPC)?
- How do I submit claims: online, by mail, or by fax? Which claim form do you need, and what documentation must be attached?
- What is the filing deadline for member-submitted claims?
Before you hang up, write down the representative’s name, the date, and the call reference number. If a claim is later processed differently than you were told, that record helps.
How much will I get back? A hypothetical example
The numbers below are hypothetical, chosen only to show the arithmetic. Your plan’s allowed amount, deductible, and coinsurance will be different.
Hypothetical plan:
- Session fee: $200 for a 60-minute session (CPT 90837)
- Plan’s out-of-network allowed amount: $120
- Out-of-network deductible: $1,000, none met yet
- Coinsurance: plan pays 60% of the allowed amount after the deductible
Step 1: Meeting the deductible. Only the $120 allowed amount counts toward the deductible, not the full $200. After eight sessions, $960 has been credited. On session nine, the first $40 of the allowed amount finishes the deductible. The remaining $80 is reimbursed at 60%, which is $48.
Step 2: After the deductible. Each session is reimbursed at 60% of $120, which is $72. Your net cost per session is $200 minus $72, or $128. That $128 is your 40% coinsurance ($48) plus the $80 difference between the fee and the allowed amount.
| Hypothetical | Sessions 1–8 | Session 9 | Session 10 onward |
|---|---|---|---|
| You pay the therapist | $200 each | $200 | $200 each |
| Credited to deductible | $120 each | $40 | $0 |
| Plan reimburses you | $0 | $48 | $72 each |
| Your net cost | $200 each | $152 | $128 each |
Two takeaways: early in the plan year you may get nothing back while the deductible fills, and the allowed amount matters as much as the coinsurance percentage. If you reach an out-of-pocket maximum, some plans then pay 100% of the allowed amount, but you’d usually still owe any difference above it.
How do I submit a superbill for out of network reimbursement?
Once you know your benefits, submission is routine. Our step-by-step guide on how to submit a superbill to insurance covers it in detail. The short version:
- Check the superbill for completeness. Insurers commonly require the provider’s name, credentials, address, NPI, and Tax ID; your name, date of birth, and member ID; ICD-10 diagnosis codes; CPT codes with dates, place of service, units, and fees; and the amount you paid. Our list of what to include on a superbill explains each field.
- Get your insurer’s claim form. Most insurers have a member reimbursement or medical claim form on their website. Some let you upload everything through the portal instead.
- Attach proof of payment if requested. A superbill that shows the amount paid usually covers this, but follow your insurer’s instructions.
- Submit and keep copies of everything, including the date you sent it.
- Watch for the EOB. Compare it to your superbill and the benefits you were quoted.
For telehealth sessions, make sure the place of service code is correct. Our guide to place of service codes for telehealth explains which codes are commonly used, though payers can differ.
How long does out-of-network reimbursement take?
There are two timelines to keep in mind.
Filing deadlines. Every plan sets a deadline for member-submitted claims, measured from the date of service. Windows vary widely, so confirm yours on the call. Missing it is one of the few mistakes that usually can’t be fixed.
Processing time. Insurers process claims at different speeds, and incomplete claims take longer because they’re returned or pended for more information. If you haven’t seen an EOB within a few weeks, check the portal or call to confirm the claim was received.
A practical habit: submit once a month. Monthly superbills keep you well inside filing deadlines and make it easy to match each EOB to a batch of sessions.
Why was my claim denied or reduced?
Common reasons include:
- No out-of-network benefits on the plan, or the service isn’t covered out of network.
- Deductible not met, so the claim processed correctly but paid $0. This isn’t a denial; the allowed amount was credited to your deductible.
- Missing or invalid information, such as no diagnosis code, a missing NPI, or a member ID typo.
- Place of service or modifier issues for telehealth sessions.
- Pre-authorization required and not obtained.
- Late submission past the filing deadline.
If you believe a claim was processed incorrectly, call to ask what’s missing and resubmit, or ask about the plan’s appeal process. Your EOB lists appeal rights and deadlines.
Should I use an out-of-network reimbursement service or app?
A category of services and apps exists to handle out-of-network claims for you. Typically they collect your superbills, file claims with your insurer, track their status, and follow up on denials. Some also estimate your benefits before you start therapy, and some partner directly with therapists.
They can save time, especially if you have many sessions or find insurer paperwork stressful. Before signing up, consider:
- Cost. Fees are structured in different ways, such as per claim, a subscription, or a percentage of what you’re reimbursed. Compare that to the time it takes you to file yourself.
- Privacy. You’ll be sharing diagnosis codes and session details. Read the privacy policy and understand how your data is stored and used.
- What’s included. Some handle appeals and follow-up; others only submit.
Many people find that once they’ve filed one or two claims themselves, the monthly routine takes only a few minutes.
Tips for therapists with out-of-network clients
If you’re the clinician, you can make reimbursement much smoother for clients:
- Provide complete superbills on a predictable schedule, ideally monthly. The therapist superbill template is preloaded with common psychotherapy codes.
- Give self-pay clients a Good Faith Estimate when the No Surprises Act requires one. See our guide to good faith estimates for therapists.
- Share the call script above so clients know what to ask before their first session.
Make your next superbill
Whether you’re a therapist preparing statements or a client who needs one, you can create a superbill for free in your browser. It flags missing fields insurers usually require, validates the NPI, and saves as a US Letter PDF ready to send with your claim. Nothing is uploaded; your data stays in your browser.
FAQ
How do I get reimbursed for out-of-network therapy?
Pay your therapist directly, ask for a superbill, and submit it to your insurance company with its member claim form or through its online portal. If your plan has out-of-network benefits, the insurer applies the claim to your out-of-network deductible and then reimburses a percentage of its allowed amount. You receive an Explanation of Benefits and, if anything is owed, a check or direct deposit.
Does out-of-network therapy count toward my deductible?
On plans with out-of-network benefits, the insurer's allowed amount for each covered session usually counts toward your out-of-network deductible. Many plans keep that deductible separate from the in-network one, and the part of your therapist's fee above the allowed amount often does not count at all. Ask your insurer how your specific plan handles it.
How long do I have to submit an out-of-network claim?
Each plan sets its own filing deadline for member-submitted claims, and the window varies widely. Call your insurer or check your plan documents for the exact limit. Submitting superbills monthly is a simple way to stay well inside any deadline.
Can my therapist submit out-of-network claims for me?
Some out-of-network therapists file claims on a client's behalf as a courtesy, but many simply provide a superbill and leave submission to the client. Third-party reimbursement services can also file for you, usually for a fee. Ask your therapist what they offer before you start.
Why did my insurer reimburse less than I expected?
Reimbursement is based on the insurer's allowed amount, not your therapist's full fee, and only after your out-of-network deductible is met. If the allowed amount is lower than the fee, your coinsurance percentage applies to that lower number. Your Explanation of Benefits shows the allowed amount, what went to the deductible, and what was paid.