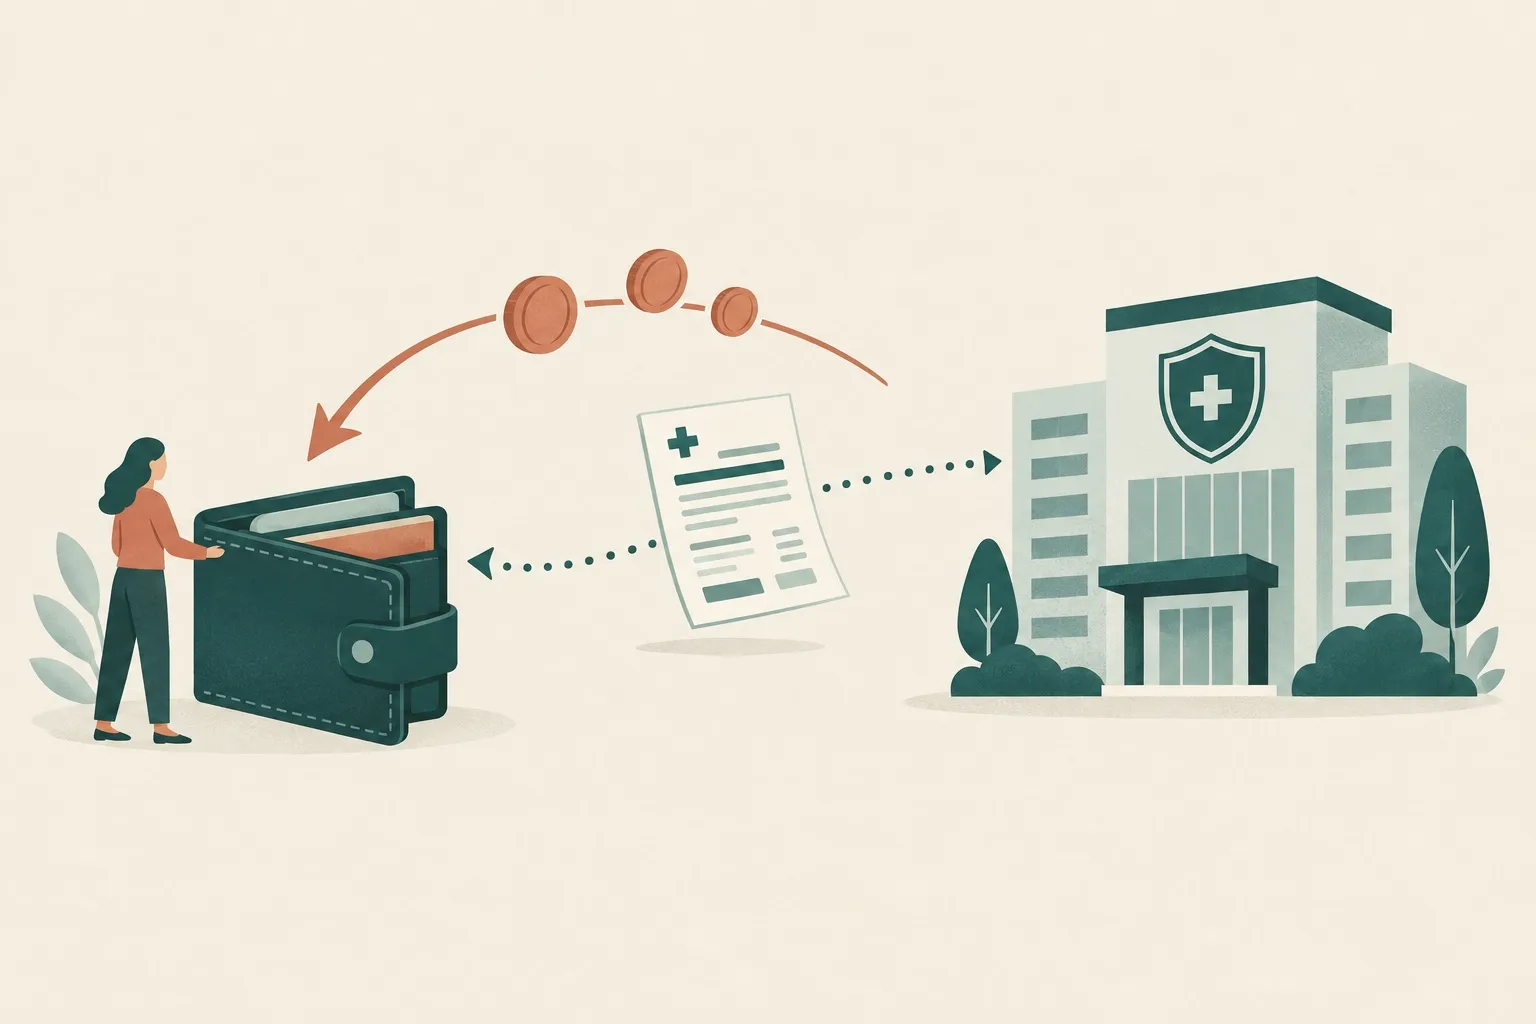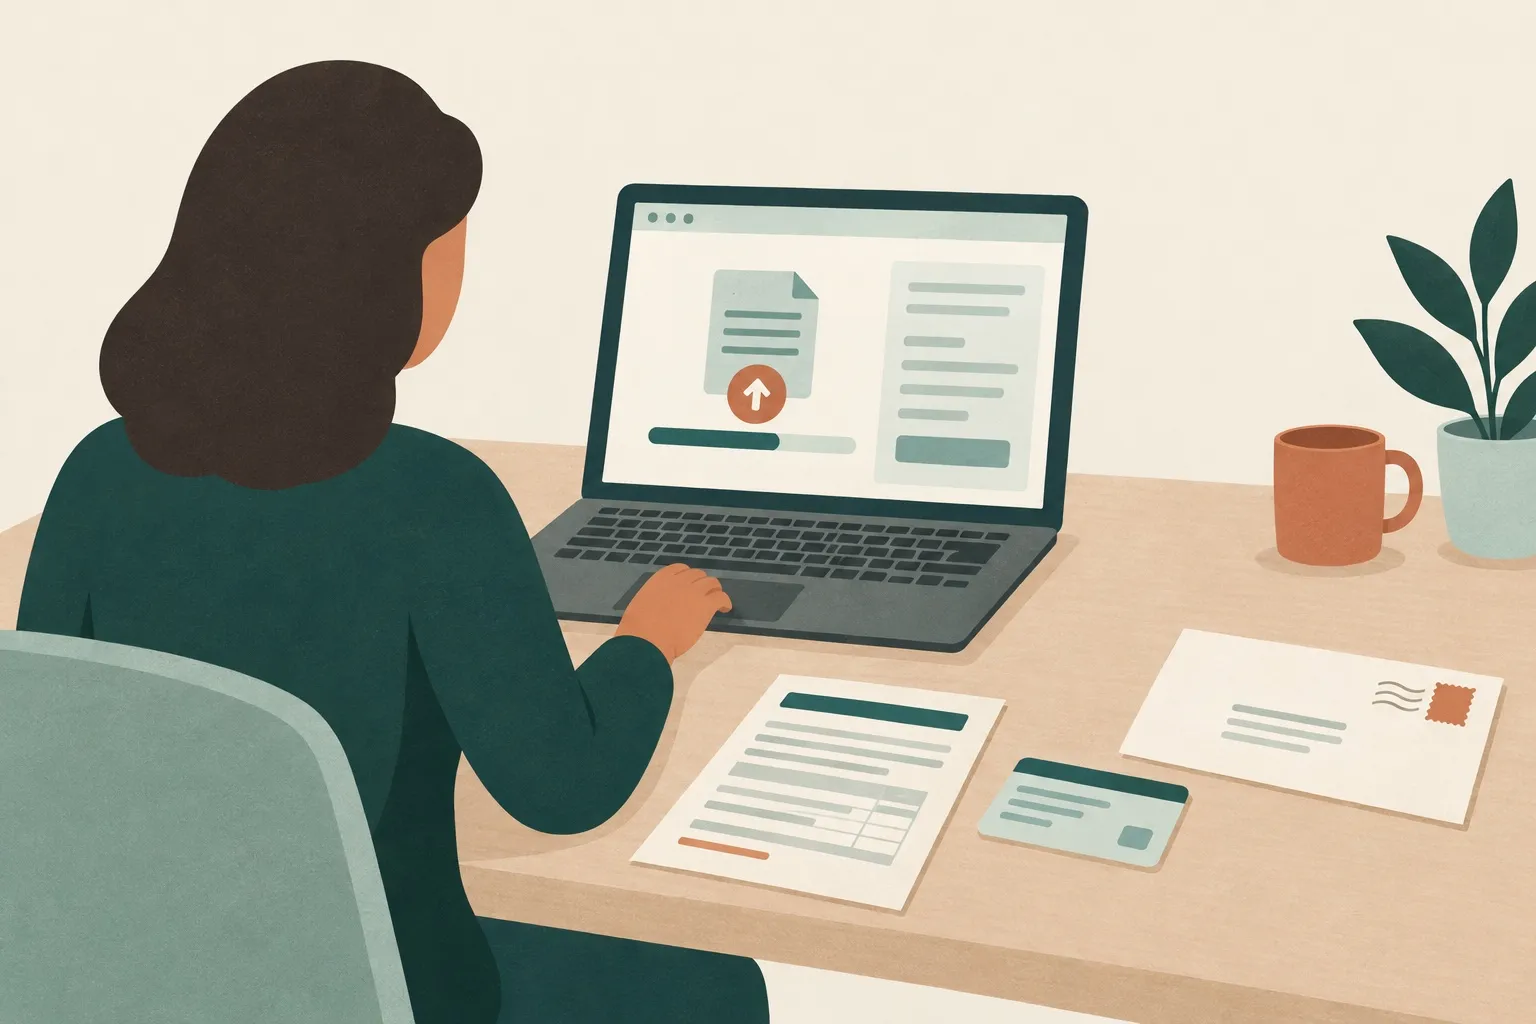
To submit a superbill to insurance, confirm your plan has out-of-network benefits, download your insurer’s member claim form, fill it out, and send it with your superbill through the insurer’s member portal, mobile app, mail, or fax. After the claim is processed, you’ll receive an explanation of benefits (EOB) and, if the claim is approved, a reimbursement payment that usually goes to you rather than the provider.
The rest of this guide walks through each step, the deadlines to watch, and how to fix the most common reasons claims get denied. If you’re new to superbills, start with what a superbill is.
Step 1: Check your out-of-network benefits
Before you file anything, find out what your plan will actually pay. Call the member services number on your insurance card, or look up your plan documents in the member portal. Ask:
- Do I have out-of-network benefits for this type of care? Many PPO and POS plans do. HMO and EPO plans usually don’t, except for emergencies.
- What is my out-of-network deductible, and how much of it have I met? On many plans the out-of-network deductible is separate from the in-network one.
- What is my coinsurance after the deductible?
- How is the allowed amount set for this CPT code? Insurers reimburse based on their allowed amount, which can be lower than your provider’s fee. Give them the exact code your provider uses, for example 90837 for an hour-long psychotherapy session.
- Is prior authorization required? Some plans require it even for out-of-network outpatient care.
- Are telehealth visits covered out of network?
- What’s the deadline to file, and where do I send claims?
Write down the date, the representative’s name, and the call reference number. If something goes wrong later, that record helps.
Step 2: Gather your documents
You’ll typically need:
- The superbill from your provider. It should list the provider’s NPI and Tax ID, your diagnosis codes, a CPT code for each service, dates of service, fees, and the amount you paid. Here’s the full list of what a superbill needs to include.
- Your insurer’s claim form. Often called a member reimbursement form or medical claim form, it’s usually in the forms section of the member portal.
- Your insurance card, for your member ID, group number, and the policyholder’s information if you’re covered on someone else’s plan.
- Proof of payment, if your insurer asks for it. A superbill that shows the amount paid and a zero balance often covers this, but some insurers want a separate receipt.
Check the superbill before you send it. A missing NPI, diagnosis code, or signature is one of the easiest ways to have a claim returned.
Step 3: Fill out the claim form
Member claim forms vary by insurer, but most ask for:
- Patient and policyholder names, dates of birth, and member ID
- Whether the care was related to an accident or injury
- Whether you have other insurance coverage
- Who should receive payment (choose yourself if you’ve already paid the provider)
- Your signature
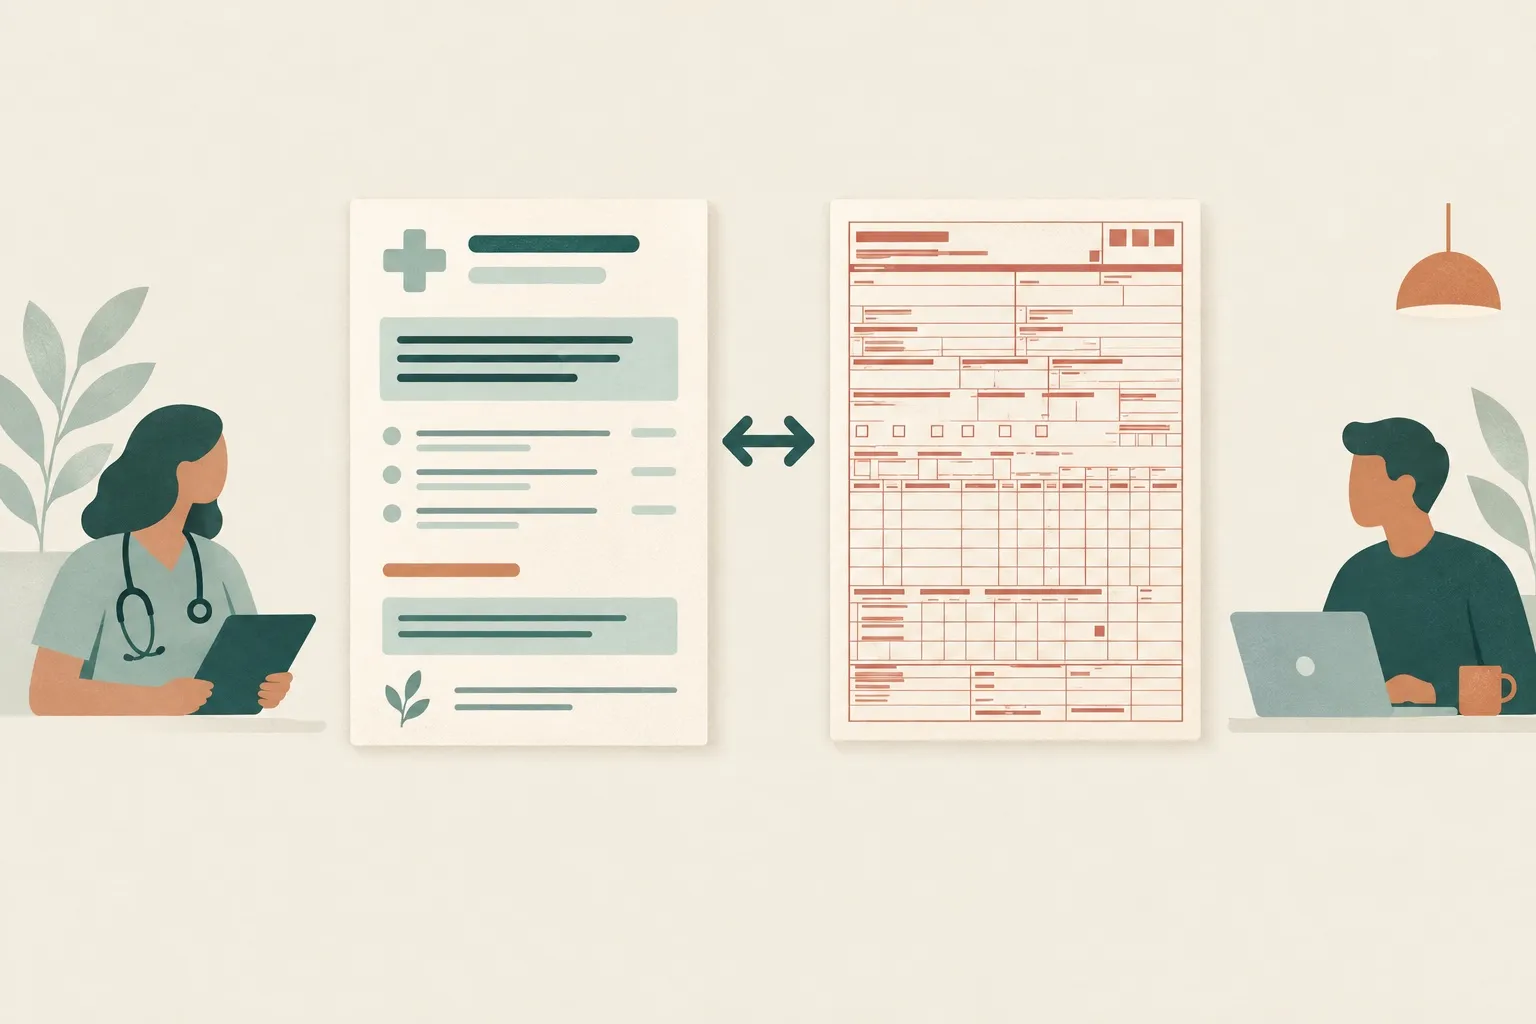
You generally don’t need to copy every code onto the form. Many forms let you write “see attached itemized bill” where they ask for services; follow the form’s instructions. A superbill is not the same thing as the CMS-1500 claim form providers use to bill insurers directly, so if your insurer mentions the CMS-1500, read superbill vs. CMS-1500 to see how they relate.
Step 4: Submit the superbill and claim form
Most insurers offer more than one way to submit. Use whichever your plan lists.
| Method | How it works | Tips |
|---|---|---|
| Member portal | Upload the claim form and superbill as PDFs or images | Easiest to track; save the confirmation number |
| Mobile app | Photograph or upload the documents | Make sure every page is legible and nothing is cropped |
| Send copies to the claims address on the form | Keep your originals; consider a trackable mailing option | |
| Fax | Fax to the number on the form, if offered | Keep the fax confirmation page |
Whichever method you choose, keep a copy of everything you send and note the date you sent it.
Can I submit several sessions at once?
Yes. Many providers issue one superbill per month listing every session. A single superbill with multiple dates of service is fine as long as each date has its own line. Batching monthly keeps the paperwork manageable, provided you stay well inside your plan’s filing deadline.
Step 5: Know your filing deadline
Every plan has a timely filing limit: the window after a date of service during which the claim must be submitted. These windows differ from plan to plan, and a claim filed late can be denied no matter how complete it is. Look for “timely filing” or “claim submission deadline” in your benefits booklet, or ask during your benefits call.
If you’re behind, submit the oldest dates of service first.
Step 6: Follow up and read your EOB
Check the claim status in your portal after you submit. If nothing appears within the timeframe your insurer gives, call to confirm they received it.
When the claim is processed, you’ll get an explanation of benefits. An EOB is not a bill; it shows how the insurer handled each service line.
| EOB term | What it means |
|---|---|
| Billed or charged amount | The fee listed on your superbill |
| Allowed amount | What the plan treats as the covered price for that service |
| Applied to deductible | The portion counted toward your deductible, which you pay yourself |
| Coinsurance | Your percentage share of the allowed amount after the deductible |
| Plan paid | What the insurer is reimbursing |
| Patient responsibility | What the plan says is your share |
If a line was applied to your deductible, it wasn’t denied. The insurer counted it toward your deductible, and later claims can start reimbursing once the deductible is met. That’s why it’s worth submitting superbills even early in the plan year.
Common superbill denial reasons and how to fix them
| Denial reason | Likely fix |
|---|---|
| Missing or invalid NPI | Ask your provider to confirm their 10-digit NPI and issue a corrected superbill |
| Missing Tax ID | Request a superbill that includes the provider’s EIN or Tax ID |
| No diagnosis code, or a service not linked to a diagnosis | Each service line needs a diagnosis pointer to an ICD-10 code |
| Member information doesn’t match | Make sure your name, date of birth, and member ID match your insurance card exactly |
| Telehealth coding issue | Ask which place of service code and modifier your insurer expects for telehealth |
| Prior authorization required | Request authorization, then ask whether earlier dates can be reprocessed |
| Service not covered or not medically necessary | Review your coverage; you can appeal with supporting documentation from your provider |
| Filed after the deadline | Appeal only if you have a documented reason the claim was late |
| Duplicate claim | Check whether an earlier submission already covered those dates |
Telehealth deserves a closer look. Insurers differ on whether they want place of service 02 or 10, and whether they want modifier 95, GT, or neither. If a telehealth line is denied, ask your insurer what it expects and share the answer with your provider. Our guide to place of service codes for telehealth explains the options.
How to appeal
If the problem isn’t a simple correction, you can appeal. Your EOB or denial letter explains how and by when. The usual approach is a written appeal that cites the claim number, explains why the service should be covered, and includes supporting documents from your provider. Keep copies of everything you send.
How to get reimbursed for out-of-network therapy
Therapy is one of the most common reasons people submit superbills, and the process is the same as above. A few extra tips for therapy clients:
- Ask your therapist which CPT code they use for your sessions before you call your insurer, so you get an accurate answer about the allowed amount.
- Ask whether superbills are issued after each session or monthly.
- Keep a simple log of submission dates, claim numbers, and amounts reimbursed.
For more on this, read our guide to out-of-network reimbursement for therapy.
For providers: make submission easy for clients
Clients get reimbursed faster when the superbill is complete the first time. Our free superbill generator validates the NPI check digit, flags missing fields insurers usually require, and can print a superbill for every client at once from an EHR or spreadsheet CSV export. Profession-specific superbill templates come preloaded with common codes.
Create a superbill now — it’s free, there’s no account, and your data stays in your browser.
FAQ
Can I submit a superbill to insurance online?
Many insurers let members submit out-of-network claims through their website or mobile app, where you upload the claim form and superbill as PDFs or photos. If your insurer doesn't offer online submission, its claim form will list a mailing address or fax number.
Do I need a claim form in addition to the superbill?
Usually, yes. Most insurers require their own member claim form, with the superbill attached as the itemized bill. Some online portals build the claim form into the upload process, so follow your insurer's instructions.
How long do I have to submit a superbill?
Each plan sets its own claim filing deadline, usually measured from the date of service. Deadlines differ between plans, so look for the timely filing rules in your benefits documents or ask member services, and submit well before the cutoff.
Who gets the reimbursement when I submit a superbill?
When you've already paid an out-of-network provider, the insurer normally pays you directly. Some claim forms ask whether to pay you or the provider, so choose yourself if you paid in full.
What should I do if my superbill claim is denied?
Start with the denial reason on your explanation of benefits. Many denials come from missing or incorrect information, which you can fix by asking your provider for a corrected superbill and resubmitting. If the insurer denied coverage itself, you can file an appeal within the deadline listed on the EOB or denial letter.